

Compass Review (RESPA Fraud, Read Warning!)
Compass Editor's Review:
As a Consumer, you will always significantly overpay for Realtor commissions, subject to hidden kickbacks and pay-to-play steering between various "Referral Fee Networks" and Compass affiliated Agents.
Compass.com (d.b.a. Compass, Inc. through the combined reach of Compass International Holdings’ real estate professionals, including @properties, Better Homes and Gardens Real Estate, CENTURY 21, Christie’s International Real Estate, Coldwell Banker, Compass, Corcoran, ERA and Sotheby’s International Realty) unlawfully agrees to pay massive RESPA-banned kickbacks to receive your information from various "Referral Fee Networks" and engages fiduciary duty fraud, false advertising, and unlawful steering practices in violation of, inter alia, 15 U.S.C. § 45, 12 U.S.C. § 2607, 12 C.F.R. § 1024.14, and as a co-conspirator in "Referral Fee Networks" racketeering activities within the meaning of 18 U.S.C. §§ 1961(1), 1961(5) & 1962(c), by using wire facilities, in violation of 18 U.S.C. § 1343 (wire fraud).
Be smart; do not allow your information to be "sold as a lead" to a double-dealing Compass Agent in exchange for massive commission kickbacks paid from your future home sale or your future home purchase.
As a consumer, you will always significantly overpay for Realtor commissions, subject to hidden kickbacks and pay-to-play steering toward Compass-affiliated agents. Compass is further engaged in unlawful kickbacks as part of an opportunity to participate in a money-making program with Rocket Mortgage.
Compass.com heavily engages in various RESPA-banned kickback schemes with a multitude of no-upfront-cost post-pay referral fee "agent-matching services" (or "referral platforms") that collect as much as 40% from Compass’ RESPA-covered real estate brokerage commissions. The kickbacks that Compass.com shells out into all such "referral networks" MUST meet certain exemptions to be lawful, and they do not meet any of them.
In the United States, RESPA firmly reads that "no person shall give, and no person shall accept any fee, kickback, or thing of value pursuant to any agreement or understanding, oral or otherwise, that business incident to or a part of a real estate settlement service involving a federally related mortgage loan shall be referred to any person." See 12 U.S.C. § 2607(a).
Compass.com unlawfully agrees to pay massive RESPA-banned kickbacks to receive Consumers’ information from various "referral networks." By working together as part of an enterprise and using interstate wire communications in furtherance of their fraudulent scheme, Compass.com acts as a co-conspirator in collusion with dozens of "referral networks" and violates the Racketeer Influenced and Corrupt Organizations Act, 18 U.S.C. § 1961, et seq. (RICO). Compass.com unlawfully agrees to pay as much as 25% to 40% of its RESPA-covered real estate commission as kickbacks into various "settlement services" referral platforms in return for referrals, conduct that violates both the plain text of 12 U.S.C. § 2607(a) and its implementing regulation.
The broker-to-broker referral exemption does not apply to these arrangements, as "referral networks" do not act as real estate brokers or perform brokerage functions in these transactions. Instead, "referral networks" sell and allocate Consumers as leads for contingent "success fees" tied to closed transactions, and perform no brokerage services in the purchase or sale of property. See 12 U.S.C. § 2607(c)(3).
The Affiliated Business Arrangement (AfBA) safe harbor also does not apply to these arrangements, because "referral networks" and participating Compass.com affiliated Agents are independent entities, not affiliates. "Referral networks" are unable to provide Consumers with compliant written AfBA disclosures when making unlawful referrals to Compass affiliated Agents. See 12 U.S.C. § 2607(c)(4).
Various "referral networks" (some, if not all, in collusion with Compass.com) act as fraudulent business enterprises with common purpose(s) of illegally profiting from the real estate commissions paid by Consumers, facilitated by a pattern of wire fraud. Almost all such "referral networks" (e.g.,
Opendoor.com Partner Program
mellohome.com (loanDepot)
Tomo.com (Moto Real Estate)
Better.com Real Estate
OwnUp.com (dba Own Up, RateGravity)
FastExpert.com
Offerpad.com HomePro
AmeriSaveRealty.com
AtClosing.com
Newzip.com (dba Realeaux)
HomeAdvantage.com
HomeStoryRewards.com
AgentFixup.com
SOLD.com
LemonBrew.com
ClosingLeads.com
55places.com
Neighborhoods.com
NavyFederalRealtyPlus.com
KelleyBlueBookHomes.com
MyAgentFinder.com (BoomTown)
HomeAndMoney.com (BoomTown)
RealEstateAgentsITrust.com Glenn Beck
RamseySolutions.com
TopAgentsRanked.com ReferralExchange
UpNest.com (Realtor.com)
PLACE.com
HomeGenius.com Radian
IdealAgent.com
RealEstateAgents.com (ReferralExchange)
HomeBuyerConnections.com
AgentPronto.com
ReferralExchange.com
Estately.com
Landed.com
HouseTea.com
HouseWhisper.ai
GetRidley.com (Ridley)
TrueParity.com
ComeHome.com (HouseCanary)
Lower.com (Movoto OJO)
NAFHomes.com (New American Funding)
ListWithClever.com (Clever Real Estate)
Realtor.com (ReadyConnect OpCity UpNest)
VeteransUnitedRealty.com (Veterans United Home Loans)
RocketHomes.com (Redfin Partner Program)
Zillow.com Preferred Flex
HomeLight.com
EffectiveAgents.com
HomesForHeroes.com
and similar sham arrangements)
utilize shell/paper brokerages in a flawed attempt to bypass 12 U.S.C. § 2607(a) kickbacks ban by falsely claiming to meet the exemption under 12 U.S.C. § 2607(c)(3).
The 12 U.S.C. § 2607(c)(3) safe harbor does NOT apply to kickbacks that Compass.com shells out into "agent-matching platforms."
In recent years, so-called "referral networks" or "agent-matching platforms" have turned the U.S. residential real estate services market into large RESPA-banned kickback schemes. Most of these networks get a shell real estate license, but they do not provide actual brokerage services. Instead, they refer home sellers and buyers to so-called "partner agents" for 25% to 40% of the agents’ commissions.
A "referral platform" may, of course, easily sell customer leads to real estate brokers. However, under law, such sales must never be tied to the outcome of the successful transaction or based on a percentage of brokerages' commissions. The US-CFPB Advisory Opinion issued on February 7, 2023, further confirms that any operator of a "settlement services" digital comparison-shopping platform receives a prohibited referral fee in violation of RESPA Section 8 when the operator receives a "thing of value" for referral activity.
For instance, in my civil lawsuit with HomeLight, the United States District Court for the Northern District of California had recently reasoned that HomeLight acts in a vertical servicer-customer relationship on a different level of the supply chain with ~28,000 partner agents.
The federal court had reasoned that HomeLight is an "upstream" supplier of paid referrals to "downstream" real estate brokers, as opposed to a real estate broker acting on the same level of distribution, where:
"To start, even though HomeLight is a licensed brokerage, in the context of this agreement HomeLight and agents are not acting as horizontal competitors agreeing to charge customers the same price for a service they both offer. … HomeLight's referral is better thought of as a vertical input to the partner agent's ultimate sale … [where] … real estate agents [are] referral platform's intermediate consumers …" HomeLight, Inc. v. Shkipin, 694 F. Supp. 3d 1242, 1250 (N.D. Cal. 2023)
This same distinction was articulated in another recent legal dispute (McLaughlin v. HomeLight, Inc.) that also clarified that HomeLight functions as a referral platform (as opposed to a real estate agent directly involved with home buyers or sellers in the purchase and sale of real estate.) That court reasoned:
"HomeLight contends that McLaughlin brings this lawsuit as an aggrieved potential consumer of its real estate agent referral service, not as a direct competitor. The Court agrees with HomeLight that McLaughlin does not plead facts supporting his conclusion that he and HomeLight are ‘direct competitors.'" McLaughlin v. HomeLight, Inc., 2:21-cv-05379-MCS (C.D. Cal. Sept. 17, 2021)
In markers that do not involve RESPA-covered settlement services, there is typically no problem with this vertical servicer-customer relationship, at a different level of the supply chain. Businesses can easily serve other businesses as their customers. However, subject to RESPA, this servicer-customer relationship designation plainly precludes 12 U.S.C. § 2607(c)(3) safe harbor applicability for any of the "referral platform" referrals of RESPA-covered "settlement services."
If you have been referred to Compass affiliated Agent by some no-upfront-cost post-pay "referral platform," you got scammed – they will provide you ~60% full service reduced with ~40% kickbacks shelled out into whichever "referral platform" made the referral. Compass affiliated Agent just sold you out for illegal kickbacks – this fact should tell you everything about Compass affiliated Agents and their integrity, or lack thereof.
Why work with criminals to help anyone buy or sell a home anywhere? I can’t think of a single reason. Granted, not every Compass affiliated Agent shells out illegal kickbacks into these "referral platforms." However, Compass (as the broker of record) is fully complicit in this RESPA fraud (because ALL Compass affiliated Agents work for and are a legal extension of Compass brokerage).
By protecting their brokerage commissions from unlawful kickbacks, honest real estate professionals always act to serve their clients with full-service value and protect their reputations. RESPA compliance is not merely the best practice for any honest professional; it is the fundamental federal law that governs the most valuable transactions in most American Consumers’ lives. Compass cardinally fails to meet this very simple standard.
As the NAR-affiliated MLS Participant, Compass.com lies about GSEs’ Interested Party Contributions (IPCs) limits applicability toward buyer-paid commissions.
Since August 17, 2024, National Association of REALTORS® (NAR)-affiliated MLS Participants have consistently and knowingly lied about the applicability of GSEs' Interested Party Contributions (IPCs) limits to buyer-paid commissions under the terms of the Gibson et al. antitrust settlement with home sellers. IPCs are contributions made by third parties with a vested interest in the transaction to cover costs that are the buyer's responsibility (See https://geodoma.com/ipcs-limits ).
This is the primary reason why "nothing has changed" in how commissions are paid and also why commissions have gone UP since the NAR settlement took effect in 2024.
See: Tuccori v. At World Properties, LLC, 1:24-cv-00150 (N.D. Ill. May 29, 2026) (Doc. 180) Geodoma's Statement in Support of Consumers
See: Sitzer/Burnett v. NAR 4:19-cv-00332-SRB (W.D. Mo. Jul. 23, 2026) (Doc. 1740) Geodoma's Statement in Support of Consumers
See: Gibson v. NAR 4:23-cv-00788-SRB [Consolidated with 4:23-cv-00945-SRB] (W.D. Mo. Jul. 27, 2026) (Doc. 930) Geodoma's Statement in Support of Consumers
See: Tuccori v. At World Properties, LLC, 1:24-cv-00150 (N.D. Ill. Aug. 7, 2026) (Doc. 193) Geodoma's Statement in Support of Consumers
See: Sitzer/Burnett v. NAR 4:19-cv-00332-SRB (W.D. Mo. Aug. 7, 2026) (Doc. 1743) Geodoma's Statement in Support of Consumers
See: Gibson v. NAR 4:23-cv-00788-SRB [Consolidated with 4:23-cv-00945-SRB] (W.D. Mo. Aug. 7, 2026) (Doc. 936) Geodoma's Statement in Support of Consumers
A viable claim for fraud under the False Claims Act (FCA) requires the false claim or statement to be "knowing" and "material." The False Claims Act defines "knowingly" to mean that a person or entity "has actual knowledge of the information; acts in deliberate ignorance of the truth or falsity of the information; or acts in reckless disregard of the truth or falsity of the information."
In other words, the False Claims Act requires more than mere negligence or a simple mistake to hold a person liable. Both "knowing" and "material" elements exist here, because the National Association of REALTORS® (NAR) knows about GSEs’ IPC limits and had explicitly requested guidance from the GSEs about the applicability of IPC limits against Gibson et al. Settlement Agreement.
However, in their response to the National Association of REALTORS® (NAR), Fannie Mae, Freddie Mac, and the FHA merely clarified the existing IPC limits guidance that "If a seller or seller's real estate agent continues to pay the buyer's real estate agent commission in accordance with local common and customary practices, these amounts are not required to be counted towards the IPC limits for the transaction." (See Real Estate Commissions Selling Notice ).
GSEs never made any "explicit confirmations that [buyer-paid] commissions for buyer agents paid by the seller would not count against the buyer" when working with NAR-affiliated MLS Participants' buyer brokers post-settlement.
On the contrary, under the Gibson et al. Settlement Agreement, buyer-paid commissions very much DO "count against the buyer" when working with NAR-affiliated MLS Participants’ buyer brokers. NAR-affiliated MLS Participants’ "knowing" and "material" lies about the GSEs’ IPC limits on applicability to NAR-affiliated MLS Participants’ buyer-paid commissions are cardinal violations of, inter alia, the False Claims Act (FCA), 31 U.S.C. §§ 3729 – 3733.
Post-settlement, NAR-affiliated MLS Participants lock homebuyers into mandated Buyer Broker Agreements (BBAs), but also tell them: "Don’t worry about it – we will just bake your buyer-paid commission cost into the purchase offer – and it does not count against you." Buyers DO NOT KNOW that this false "does not count against you" notion also means that NAR-affiliated MLS Participants subject them to IPCs fraud (since August 17, 2024.) NAR-affiliated MLS Participants’ illegal conduct further destroys homebuyers’ Article III Constitutional standing to raise a RESPA claim to keep their buyer-paid commissions free from illegal kickbacks.
Compass.com engages in vertical price-fixing as a "spoke" at different levels of a supply chain with certain "agent-matching platforms."
As a RICO/RESPA co-conspirator, Compass.com also engages in vertical price-fixing as a "spoke" at different level of a supply chain with select "referral networks," in which "referral networks" acting as "hubs" establish the total commissions all "partner brokers" must charge under the terms of their referral agreements (in addition to having to illegally remit agreed-upon percentages of their RESPA-covered commissions to "referral networks" as platform advertising fees paid for leads).
mellohome.com (loanDepot) expressly price-fixes buyer rebates and listing commission terms between homebuyers and home sellers and a network of third-party real estate agents with a program called Grand Slam.
Better.com Real Estate price-fixing of buyer broker rebates violates Section 1 of the Sherman Antitrust Act. Better.com Real Estate aims to stabilize real estate buy-side commission rates for ALL partner agents with dismal, price-fixed buyer-broker rebate offers.
AmeriSaveRealty.com expressly price-fixes buyer rebate terms between homebuyers and a network of third-party real estate agents.
Newzip.com price-fixing of buyer-broker rebates violates Section 1 of the Sherman Antitrust Act. Newzip.com aims to stabilize real estate buy-side commission rates for ALL partner agents with dismal, price-fixed buyer-broker rebate offers.
HomeAdvantage.com price-fixing of buyer-broker rebates violates Section 1 of the Sherman Antitrust Act. HomeAdvantage.com aims to stabilize real estate buy-side commission rates for ALL partner agents with dismal, price-fixed buyer-broker rebate offers.
HomeStoryRewards.com price-fixing of buyer-broker rebates violates Section 1 of the Sherman Antitrust Act. HomeStoryRewards.com aims to stabilize real estate buy-side commission rates for ALL partner agents with dismal, price-fixed buyer-broker rebate offers.
NavyFederalRealtyPlus.com price-fixing of buyer-broker rebates violates Section 1 of the Sherman Antitrust Act. NavyFederalRealtyPlus.com aims to stabilize real estate buy-side commission rates for ALL partner agents with dismal, price-fixed buyer-broker rebate offers.
MyAgentFinder.com price-fixing of buyer-broker rebates violates Section 1 of the Sherman Antitrust Act. MyAgentFinder.com aims to stabilize real estate buy-side commission rates for ALL partner agents with dismal, price-fixed buyer-broker rebate offers.
HomeAndMoney.com price-fixing of buyer-broker rebates violates Section 1 of the Sherman Antitrust Act. HomeAndMoney.com aims to stabilize real estate buy-side commission rates for ALL partner agents with dismal, price-fixed buyer-broker rebate offers.
ReferralExchange.com price-fixing violates Section 1 of the Sherman Antitrust Act. ReferralExchange.com model is also materially deceptive because it aims to stabilize real estate buy-side commission rates for ALL partner agents at a 3% commission rate.
HomeGenius.com scheme further violates Section 1 of the Sherman Antitrust Act with illegal price-fixing. HomeGenius.com model is materially deceptive because it aims to utilize price-fixed rebates paid to the homebuyer at a dismal 15%.
IdealAgent.com price-fixing violates Section 1 of the Sherman Antitrust Act. IdealAgent.com model is also materially deceptive because it aims to stabilize real estate commission rates for ALL partner agents at 2% of the sales price.
NAFHomes.com operates with a sole purpose to collect illegal referral fees by setting an equivalent of $2,500 rebates for third-party brokers across the United States.
ListWithClever.com (Clever Real Estate) is presented to consumers as a "savings" program. In reality, this is a price-fixing scheme that uses unlawful price-fixing and illegal kickbacks to deliver a false appearance of savings.
VeteransUnitedRealty.com (Veterans United Home Loans) engages in price-fixing because it needs a "dangling carrot in front of consumers" to "reasonably" justify the kickbacks it takes from the brokers who participate in the scheme, acting as a hub in a hub-and-spoke conspiracy.
RocketHomes.com price-fixing of terms, called BUY+ rewards, entices consumers with false savings.
HomeLight.com price-fixing violates the Sherman Antitrust Act. HomeLight's model is also materially deceptive because it aims to stabilize real estate commission rates for ALL partner agents at 5%-6% of the sales price as the standard range.
According to the US-FTC Guide to Antitrust Laws, price fixing is an agreement (written, verbal, or inferred from conduct) among competitors to raise, lower, maintain, or stabilize prices or price levels. The antitrust laws require that each real estate brokerage establish prices on its own. A "hub-and-spoke" conspiracy among real estate brokers to fix commissions is almost always illegal, whether fees are specified at a minimum, maximum, or within some range. Real estate brokers that knowingly enter into "hub-and-spoke" price-fixing agreements are routinely investigated by federal law enforcement agencies and can be criminally prosecuted. Potential penalties include lengthy terms of imprisonment (up to ten years) and large fines (up to $1 million for individuals, $100 million for companies). A defendant is allowed to argue that there was no agreement, but if the government or a private party proves a plain price-fixing agreement, there is no defense to it. Defendants may not justify their behavior by arguing that the price-fixed real estate commissions were reasonable to purchasers, were necessary to avoid cut-throat competition, or stimulated competition.
Compass CEO, Robert Reffkin KNOWS that the kickbacks shelled out into "agent-matching platforms" are illegal.
On May 21, 2026, Compass CEO Robert Reffkin openly admitted in thier LinkedIn post that criticizes Zillow Preferred (Flex) that they KNOW about the illegality of thier conduct as the following:
Under Illinois law, brokerages are responsible for supervising how listings are marketed to consumers, and directly submitting listings to Zillow creates legal and regulatory risk for both the brokerage and agents. Specifically, Illinois law prohibits advertising, "whether in print, via the Internet, or through social media, digital forums, or any other media" that is "fraudulent, deceptive, inherently misleading, or proven to be misleading in practice." Zillow is facing a federal class-action lawsuit accusing it of deceptive marketing and illegal business practices. The lawsuit, on behalf of a class of homebuyers, alleges that Zillow "tricks" users clicking "contact agent" buttons into using Zillow-affiliated agents rather than the home's actual listing agent, while hiding a steep 40% commission referral fee that inflates home prices.
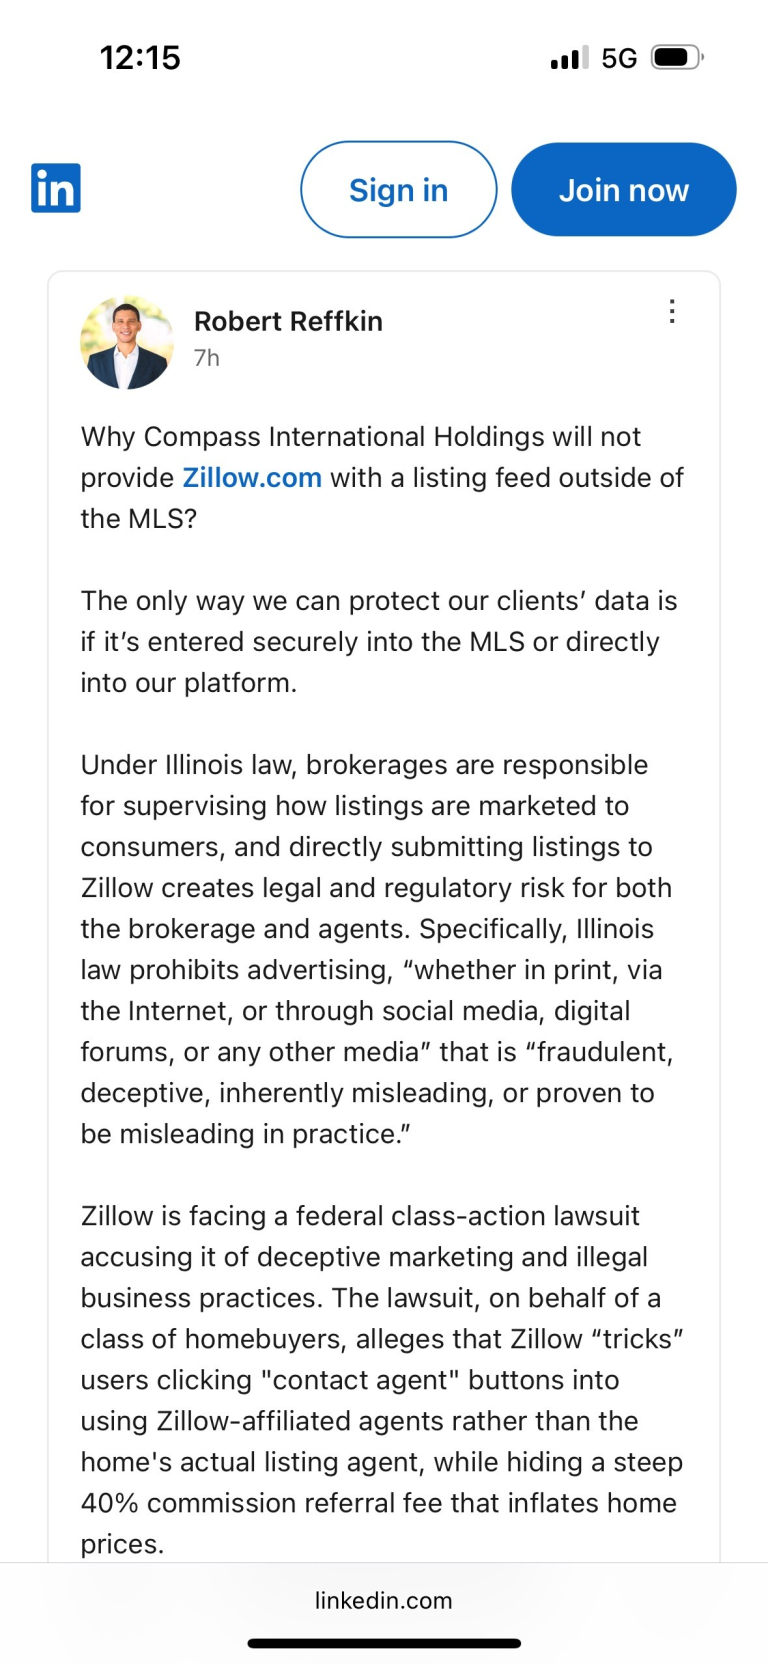
Robert Reffkin admits that they KNOW that Zillow Preferred (Flex) 40% kickbacks are illegal under RESPA. Yet, Compass itself shells out illegal kickbacks into Zillow Preferred (Flex), same as every major brokerage in America.
The 12 U.S.C. 2607(c)(4) AfBA safe harbor does NOT apply to Rocket/Compass so-called "historic alliance."
Compass is also involved in a highly specific RESPA fraud with Rocket Mortgage as following:
High-Intent Lead Pipeline: Over the term of the partnership, Compass International Holdings real estate professionals will gain access to more than 1 million buyer inquiries generated through Redfin, giving them more opportunities to build relationships and support buyers as they move toward a purchase. Redfin agents will benefit from increased consumer traffic driven by a broader selection of homes — creating more opportunities to engage buyers earlier in their journey.
(Source: Compass and Rocket Form Historic Alliance to Dramatically Increase Home Listing Inventory on Redfin )
There are a number of legal reasons why this arrangement is illegal, starting with lack of AfBA disclosure statement that must be given to meet the AfBA safe harbor
(See Affiliated business arrangements ) and ending with the fact that the thing of value is exchanged between Rocket Mortgage and Compass for referrals as part of an opportunity to participate in a money-making program with Rocket Mortgage.
Incidentally, Compass has a 100% lawful joint venture (JV) called OriginPoint, formed in 2021 with a lender Guaranteed Rate (now known as Rate)
(See Compass and Guaranteed Rate Join Forces to Announce the Launch of OriginPoint/ ),
so they KNOW how to form lawful AfBAs – they just chose not to do that with Rocket Mortgage. I guess, its easier to break the cardinal law in real estate and defraud their clients with Rocket Mortgage steering, for whatever reason. This scam is off the rails – each RESPA violation carries a year in federal prison and a $10,000 fine. None of these people would EVER get out of prison, if the law is to become enforced against them by our government.
Compass admits in their 2025 Annual Report Form 10-K that they are fully-aware of the Zillow Preferred (Flex) litigation.
Compass, Inc. in their Form 10-K for the fiscal year ended December 31, 2025 states:
"RESPA also has been invoked by plaintiffs in private litigation for various purposes and some state authorities have also asserted enforcement rights. Ongoing private litigation in our industry reflects increasingly expansive interpretations of RESPA as applied to referral fee programs, lead distribution, and affiliated-service arrangements." (See Source )
This seemingly blanket legal disclosure (and a vague reference to the Alucard Taylor, et al. v. Zillow Group, Inc., et al. Case No.: 2:25-cv-01818 class action lawsuit) attempts to hide the full-blown RESPA liability for Compass (Compass employs very well-paid lawyers: they KNOW that this is a major legal fallout – the entire brokerage is built on illegal kickbacks – this is a felony).
In fact, in 2025, Zillow offered Compass a $1.3 billion to $1.6 billion annual "revenue uplift" – in exchange for ~40% kickbacks shelled out from Compass into Zillow. This, alone, is ~$640,000,000 in illegal kickbacks being discussed. Even though Compass declined this deal, it exposes the overall problem – there are thousands of Compass agents who shell out illegal kickbacks into Zillow Preferred (Flex) as well as (50)+ other referral fee programs.
There is no such thing as a "referral fee program" under RESPA – referral fees are illegal in U.S. residential real estate markets. The so-called "expansive interpretations" is nothing more than Compass brokers (kickback-paying criminals, starting with Reffkin) getting caught (in RESPA/RICO collusion with Zillow Preferred (Flex), Rocket Homes, Veterans United Realty, etc.) violating the law hundreds of thousands (if not millions) of times – that carries a year in federal prison, for each violation.
Compass, to "double-end" their commissions with a 3-Phase Marketing (3PM) strategy, steers their own buyer clients toward pre-marketed listings that Compass KNOWS are overpriced by 2.9%.
Compass's 3PM listings strategy delays the submission to MLSs in an effort to "game" the MLS participation. In fact, ~94% of all Compass 3PM listings continue to MLS, and only ~6% of homes are sold in the "pre-marketing" phase. If the home seller could not utilize the final MLS phase, they would never agree to the 3PM listings strategy. Compass's 3PM listings strategy is not off-MLS listings, but delayed-MLS listings strategy that fails (and is designed to fail) ~94% of the time.
The Compass research assessed Compass sell-side residential transactions from January 1, 2024, through December 31, 2024, finding that:
"Homes pre-marketed as Compass Private Exclusives and/or Compass Coming Soon before going active on the MLS were associated with an average 2.9% higher close price compared to those that were not pre-marketed." (See Source )
In these ~6% of Compass 3PM home sales that actually do sell in pre-marketing phase, Compass favors the home seller by initially overpricing 3PM listings by 2.9%. Pre-marketed listings do not have to be priced lower because there are no "Days on Market" and "Price History" associated with pre-marketing. Pre-marketed listings allow home sellers to list their home for 2.9% more without the downside of the MLS-tracked metrics. Alas, this also means that Compass (when it represents both the home seller and the homebuyer) must steer BUYER clients toward homes that they KNOW are overpriced by 2.9% to double-end the deal. This conduct violates the fiduciary duty to BUYER clients, by self-admission on the Compass website.
The math is such that with these ~6% of Compass 3PM home sales, Compass BUYER clients, statistically, overpay for homes by about $200 million a year – even though Compass holds a fiduciary duty to treat both their buyer and seller clients fairly.
July 8, 2026 Update – Also see Geodoma's Amicus in Zillow Group, Inc. v. Midwest Real Estate Data LLC (1:26-cv-05451) N.D. Illinois Lawsuit below:
See Zillow v. MRED 1:26-cv-05451 (N.D. Ill.) Geodoma's Statement in Support of Neither Party (Doc. 132)
See Zillow v. MRED 1:26-cv-05451 (N.D. Ill.) Geodoma's Statement in Support of Neither Party (ECF 123)
See Zillow v. MRED 1:26-cv-05451 (N.D. Ill.) Geodoma's Statement in Support of Neither Party (ECF 109)
About Compass Review
This is a genuine, independent, and unpaid editorial review for Compass brokerage. There are no commercial agreements (paid or otherwise) between the author and the reviewed business.
Compass Brokerage was explicitly notified about this editorial review.
Updated October 4, 2026 Compass.com Review – Final Notice of Publication.
Although Compass Brokerage is not required to respond, the author did not receive any formal correction notices or objections. This, in effect, means that Compass Brokerage is unable to formally address its illegal conduct.
Compare Compass with competing real estate brokerages
(such asSide.com
TheJasonMitchellGroup.com
LPTRealty.com
UnitedRealEstate.com
HomeSmart.com
NextHome.com
FathomRealty.com
WestUSA.com
RealtyExecutives.com
TheAgencyRE.com
SERHANT.com
Corcoran.com
Intero.com
RealtyOneGroup.com
SothebysRealty.com
ERA.com
ColdwellBanker.com
ChristiesRealEstate.com
CENTURY21.com
BHGRE.com
atProperties.com
Anywhere.re
VyllaHome.com
Windermere.com
EVrealestate.com
HowardHanna.com
oneREAL.com
KW.com
Elliman.com
BHHS.com
HomeServices.com
eXpRealty.com
REMAX.com ).
Contact Compass:
New York, NY 10011 US
About the Author
Dmitry Shkipin operates Geodoma and is a well-known critic of illegal referral fees charged by so-called "paper brokerages" that organize real estate agents into "referral fee networks" and don't actually buy and sell property.
The information presented in this review is 100% accurate and an objective analysis of massive and ongoing RESPA fraud in the U.S. residential real estate industry.
The so-called "no upfront costs referral networks," "agent-matching services," "pay-at-close companies," and "referral fee programs" are not genuine brokerages acting in a brokerage capacity.
(Source: Opinion: Broker-to-broker referral exemption does not apply to agent-matching platforms )
Every year, illegal RESPA-banned referral fees from so-called "paper brokerages" inflate real estate commissions by $15B.
(Source: Referral fees from so-called 'paper brokerages' including Zillow inflate commissions by $15B: HomeOpenly )
Thank you!
Your review has been successfully received. Please allow 24 hours for your review to become available.
Feel free to contact us if you need further assistance. At Geodoma we aim to make the opportunity of homeownership transparent, affordable and an open experience.